Commercial Due Diligence Guide: Financial Review, Operations, and Risk Assessment
Commercial due diligence is a structured review of a business, commercial asset, or transaction before an important financial or strategic decision. It can help stakeholders understand financial performance, operational conditions, contractual obligations, potential liabilities, and material risks.
Due diligence is commonly associated with acquisitions, investments, financing, partnerships, commercial real estate transactions, and major business restructurings. The scope depends on the transaction and the information available.
Why Commercial Due Diligence Matters
A transaction may appear financially attractive based on limited information, while deeper review can reveal obligations or risks that require further analysis.
Commercial due diligence can help examine:
Financial performance
Revenue and earnings quality
Assets and liabilities
Contracts
Operations
Customers and suppliers
Employees and organizational structure
Regulatory compliance
Litigation exposure
Technology and cybersecurity
Intellectual property
Tax matters
Insurance coverage
Business continuity
The purpose is generally to develop a more complete understanding of the transaction rather than relying solely on management summaries or headline financial figures.
Financial Due Diligence
Financial review is often one of the central components of commercial due diligence.
Documents may include:
Income statements
Balance sheets
Cash-flow statements
General ledgers
Bank records
Accounts receivable
Accounts payable
Tax filings
Budgets
Forecasts
Debt schedules
Capital expenditure records
Reviewers may examine whether reported financial performance is consistent with underlying records and whether unusual or nonrecurring items materially affect results.
Revenue and Earnings Analysis
Revenue should be evaluated in the context of how the business actually generates income.
Analysis can include:
Revenue by product or business segment
Recurring versus nonrecurring revenue
Customer concentration
Contract duration
Revenue recognition practices
Refunds or adjustments
Historical growth
Gross margins
Operating margins
Earnings adjustments
A detailed review can help distinguish sustainable operating performance from temporary or unusual financial effects.
Working Capital and Cash Flow
Working capital analysis examines the relationship between short-term assets and obligations.
Relevant areas may include:
Accounts receivable aging
Inventory levels
Accounts payable
Accrued expenses
Deferred revenue
Operating cash flow
Seasonal fluctuations
Working-capital requirements
Cash-flow analysis can also identify differences between reported earnings and actual cash generation.
Operational Due Diligence
Financial information provides only part of the picture. Operational review examines how the business functions in practice.
Areas can include:
Business processes
Production capacity
Facilities
Equipment
Technology systems
Supply chains
Procurement
Inventory management
Quality controls
Workforce structure
Operational dependencies
Business continuity
The review should consider whether existing operations can support the organization's current activities and anticipated changes.
Customer and Supplier Risk
Customer and supplier relationships can materially affect business stability.
Due diligence may examine:
Customer concentration
Major customer agreements
Contract renewal dates
Supplier concentration
Supplier dependencies
Pricing provisions
Termination rights
Geographic exposure
Performance obligations
Dispute history
Heavy reliance on a small number of customers or suppliers can create concentration risk that should be understood before a transaction.
Contract Review
Contracts can create important rights and obligations that may continue after a transaction.
Review areas may include:
Major customer contracts
Supplier agreements
Lease agreements
Financing documents
Licensing agreements
Technology agreements
Distribution arrangements
Partnership agreements
Change-of-control provisions
Termination provisions
Renewal provisions
Assignment restrictions
Some agreements may require consent or notification when ownership or control changes.
Legal and Regulatory Risk
Due diligence can identify legal and regulatory matters that may affect a transaction.
Potential review areas include:
Pending litigation
Regulatory investigations
Licenses
Permits
Compliance records
Intellectual-property disputes
Employment claims
Environmental obligations
Data-protection requirements
Industry-specific regulations
The relevant requirements depend on the industry, location, entity structure, and transaction.
Tax Due Diligence
Tax review can examine historical filings and potential liabilities.
Areas may include:
Federal tax filings
State and local taxes
Payroll taxes
Sales and use taxes
Property taxes
Tax audits
Tax disputes
Deferred tax matters
Tax credits
International tax obligations
Tax exposure should be evaluated with current rules and the specific transaction structure in mind.
Technology and Cybersecurity Review
Technology systems can represent both business assets and operational risks.
A technology review may examine:
IT infrastructure
Software licenses
Data architecture
Cybersecurity controls
Access management
Backup procedures
Incident history
Cloud systems
Vendor dependencies
Software contracts
Data-protection practices
Cybersecurity incidents or weak controls can affect operations, compliance obligations, financial exposure, and transaction planning.
Human Resources and Workforce Review
Workforce analysis can provide information about organizational continuity and potential employment obligations.
Review areas may include:
Employee agreements
Compensation structures
Benefit arrangements
Key personnel
Workforce concentration
Employment claims
Contractor relationships
Incentive arrangements
Employee turnover
Policies and procedures
Key-person dependencies may require additional continuity planning.
Insurance and Risk Transfer
Insurance records can help identify how significant business risks are currently addressed.
Documents may include:
General liability policies
Property coverage
Cyber coverage
Professional liability coverage
Directors and officers coverage
Workers' compensation records
Claims history
Policy limits
Major exclusions
Insurance coverage should be evaluated alongside the actual risk profile rather than assumed to eliminate potential exposure.
Asset and Property Review
Physical and intangible assets may require separate examination.
Asset review can include:
Real estate
Equipment
Vehicles
Inventory
Intellectual property
Software
Licenses
Trademarks
Domain names
Data assets
Specialized machinery
Ownership, condition, valuation, liens, restrictions, and documentation can all be relevant.
Risk Assessment Framework
A structured risk register can help organize findings.
| Risk Area | Review Focus |
|---|---|
| Financial | Earnings, cash flow, debt, working capital |
| Operational | Processes, capacity, dependencies |
| Legal | Contracts, litigation, obligations |
| Regulatory | Licenses, permits, compliance |
| Tax | Filings, liabilities, audits |
| Technology | Systems, cybersecurity, data |
| Workforce | Employees, key personnel, claims |
| Commercial | Customers, suppliers, market exposure |
| Assets | Ownership, condition, restrictions |
| Insurance | Coverage, exclusions, claims |
Risks can then be categorized according to their potential significance, probability, available evidence, and possible mitigation measures.
Due Diligence Data Room
A secure data room can organize documents for review by authorized parties.
Typical categories include:
Corporate records
Financial statements
Tax records
Contracts
Property records
Employee documents
Insurance policies
Regulatory documents
Intellectual-property records
Technology documentation
Litigation records
A well-organized data room can make it easier to track missing documents and maintain a record of reviewed information.
Recent Developments
Commercial due diligence increasingly includes technology, cybersecurity, data privacy, supply-chain resilience, and environmental considerations.
Artificial intelligence can also create new review questions, including:
Ownership of AI-generated or AI-assisted materials
Use of third-party AI platforms
Confidential information exposure
Data-processing practices
Software licensing
Model-related dependencies
Internal AI governance
Organizations involved in transactions may also examine climate-related exposure, supply-chain concentration, and operational resilience where these factors could materially affect the business.
Commercial Due Diligence Planning Checklist
Before completing a review, consider:
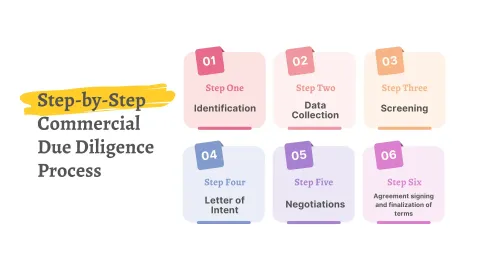
Define the transaction and review objectives
Establish the due-diligence scope
Collect financial records
Review revenue and earnings
Analyze working capital and cash flow
Review major contracts
Examine customers and suppliers
Assess operational processes
Review legal and regulatory matters
Examine tax records
Review technology and cybersecurity
Assess workforce matters
Review insurance coverage
Verify major assets
Identify key risks
Document unresolved questions
Establish follow-up procedures
Tools and Resources
Useful due-diligence resources can include:
Financial statements
General ledger reports
Tax filings
Contract repositories
Corporate records
Secure data rooms
Business valuation reports
Risk registers
Insurance policy records
Asset registers
IT and cybersecurity assessments
Compliance records
Customer and supplier concentration reports
Legal documentation
Professional accounting and legal reviews
Frequently Asked Questions
What is commercial due diligence?
Commercial due diligence is a structured review of financial, operational, legal, commercial, technological, and other factors before a significant business or investment decision.
What does financial due diligence examine?
Financial due diligence can examine financial statements, revenue, earnings, cash flow, working capital, debt, taxes, accounting records, and other information relevant to the transaction.
Why are contracts important in due diligence?
Contracts can establish continuing obligations, termination rights, renewal provisions, assignment restrictions, and change-of-control requirements that may affect a transaction.
How does operational due diligence work?
Operational due diligence examines processes, facilities, technology, workforce, suppliers, production capabilities, dependencies, and continuity arrangements to understand how the business operates.
Who typically performs commercial due diligence?
Depending on the transaction, due diligence can involve accountants, attorneys, financial professionals, industry specialists, technology professionals, valuation experts, tax professionals, and other qualified advisers.
Conclusion
Commercial due diligence provides a structured way to examine the financial condition, operations, contracts, assets, liabilities, technology, workforce, and risks associated with a business or transaction.
A thorough review combines financial analysis with operational, legal, regulatory, commercial, technology, and risk considerations. The appropriate scope depends on the transaction, industry, jurisdiction, and information available.
Significant transaction decisions should be based on current documentation and appropriate professional review rather than a limited set of financial or operational indicators.

Related Post...
Corporate Relocation Planning Guide: Office Transfers, Workplace Logistics, and Operations
Updated: September 16, 2026
Read More
Franchise Territory Planning Guide: Location Rights, Market Research, and Expansion
Updated: September 17, 2026
Read More
Business Continuity Testing Guide: Recovery Exercises, Risk Reviews, and Operations
Updated: September 16, 2026
Read More